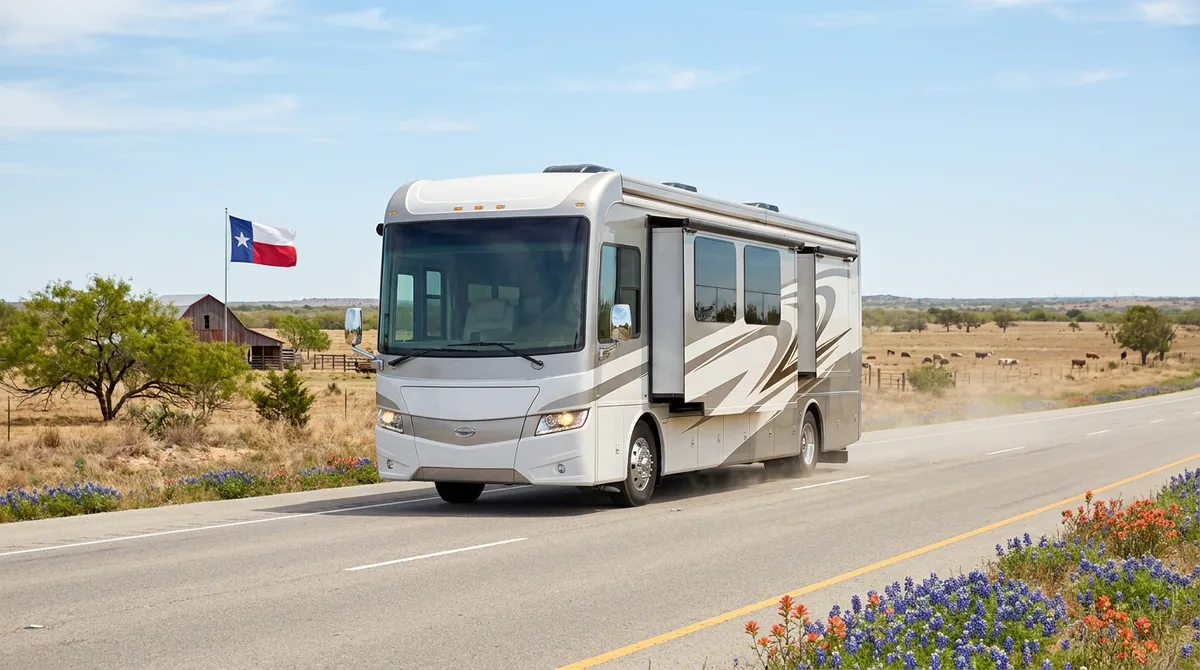
Two policies you already own. Neither one covers the toys.
Here is the assumption that costs Texas owners the most: "the truck's insured and the house is insured, so the stuff they tow and store must be too." Your auto policy lends its liability to a trailer only while it is hitched, and never covers the trailer's own damage. Your homeowners policy extends a little coverage to small, low-powered craft, and stops entirely at anything with a real motor — especially once it leaves the driveway or floats a liability claim on open water.
So the toys get their own coverage, matched to what they are. A motorhome is a vehicle and a house at once: 30/60/25 liability because Texas registers it like a car, physical damage because a Class A is a rolling six-figure asset, and vacation liability for the half of its life it spends parked with you living in it. A travel trailer needs its own physical damage policy for the hail, the blowover, and the storage-lot theft. A boat on Lake Travis, Lake Conroe, or a Gulf Coast bay answers to the marina and the lender more than the state, and the smart package includes fuel spill and wreck removal, because a sunk boat creates bills that float.
Two Texas notes. This is the most popular full-timer domicile state in the country — if the rig is your residence, full-timer coverage replaces the homeowners policy you no longer have, and running a recreational policy on a full-time rig is a claim dispute on layaway. And Texas weather works overtime: hail in one of the most hail-prone states in the country, flash floods from the Hill Country to Houston, hurricanes on the coast, wildfire risk out west, and hard freezes like Winter Storm Uri in February 2021, which is why comprehensive on a stored rig is the coverage that quietly earns its premium all year.
Tell us what is in the driveway and what is in the slip. One call, one team, the whole fleet — and bundling may help with the total.